Showing posts with label Financial Institutions. Show all posts

Friday, December 23, 2011

Film Review: Margin Call

Margin Call directed by J.C Chandor (Before The Door Pictures, Benaroya Pictures, Washington Square Films, R, 107 minutes)


A Financial Crisis

Margin Call catalogues a thirty-six hour period of the events that took place at a prestigious investment firm, which looks similar to the notorious firm Lehman Brothers. Through the lens of the firm, the audience gets to see the financial crisis of 2007-2008, and how investment bankers handled the crisis. The film also had what I considered to be a particularly stellar cast, including Kevin Spacey, Stanley Tucci, and Jeremy Irons. I was excited to see this movie, though I had a feeling that any movie surrounding the financial crisis might be a bit over my head – and (spoiler!) it was. So, with a great sense of forthcoming confusion, I embarked into this movie.

The Wrong Place at the Wrong Time

The movie begins with our three protagonists, junior employees Seth Bregman (Penn Badgley) and Peter Sullivan (Zachary Quinto) as well as fixed income salesman Will Emerson (Paul Bettany). These three watch as the Human Resource department walks from floor to floor conducting mass layoffs in the wake of the financial crisis. Their boss from risk management, Eric Dale (Stanley Tucci), is one of the first employees to be laid off. As Eric packs up his belongings, he hands a USB drive to Peter, warning him to “be careful”.
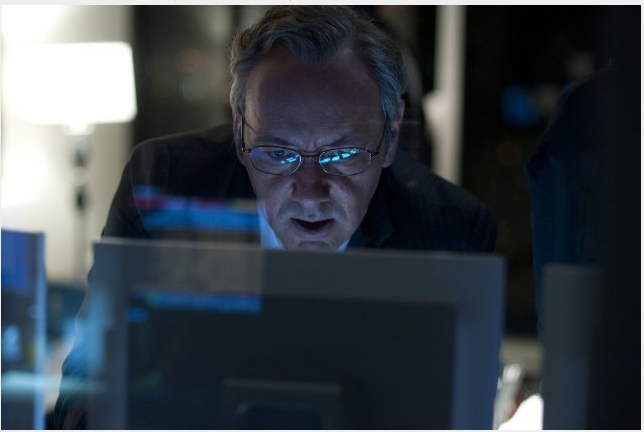
Photo by Walter Thompson
Obviously distraught by the warning, and in lieu of celebrating with his still-employed teammates, Peter, a doctorate in aeronautical engineering, remains in the office crunching numbers and trying to figure out why Dale told him to be careful. He discovers, to his horror, that trading will soon exceed historical volatility levels via the Value at Risk (VaR) system. The VaR system notifies risk managers about the danger of loss on a specific portfolio of financial assets. The company’s assets – mortgage backed securities – are in danger because of excessive leverage (borrowing too much money). If the firm’s assets decrease by twenty five percent, the business (again remember, the story represents Lehman Brothers) will suffer a loss greater than its market capitalization (the value of the share for the company times the number of shares outstanding). 

Coming to this realization, Peter tells his coworkers, and his boss, the head of sales, Sam Rogers (Kevin Spacey).

An Unsettling Option

Photo by Walter Thompson
The head of risk management, Sarah Robertson (Demi Moore), head of securities, Jared Cohen (Simon Baker), and CEO John Tuld (Jeremy Irons,) meet with the three main characters all night long. John, the CEO, finally reveals his unsettling plan: first, the firm will sell all of its bad shares before the market can react to the dim reality that the shares are completely worthless; and second, he will offer Sarah Robertson (the head of risk management) up as a sacrifice to appease members of the board, much to her dismay.


Uneasy with the plan to start, Sam Rogers switches tunes when he discovers that he and his traders will receive seven figure bonuses if they achieve a 93% or greater reduction of mortgage-backed securities  assets.


Don’t Forget Your Financially Savvy Father-in-Law

I would have enjoyed this movie quite a bit more if it weren’t so complicated. The cast helped pique my interest, but if I hadn’t had my financially-savvy father-in-law watching the movie with me explaining things like mortgage-backed securities, value at risk, and leverage systems, I would have been completely lost as the plot unfolded.

The cast delivered a compelling performance, but perhaps for the not-so-financially-brilliant folks out there, Margin Call isn’t the movie for you.  If, however, you’ve mastered the financial jargon, I think it is worth a view.

Verdict: 2 out of 5

Posted by: Andrew Jacobson
---
Affiliate Links:

Friday, April 8, 2011

Book Review: Banker to the Poor

Banker To The Poor: Micro-Lending and the Battle Against World PovertyBanker to the Poor: Micro-Lending and the Battle against World Poverty by Muhammad Yunus (New York: Public Affairs, 1999. 312 pp)

Born in 1940, Muhammad Yunus grew up in the Bengal Province of British India (now Bangladesh). Yunus studied economics at Dhaka University receiving a B.A. and M.A. in the field. Afterward, he accepted a Fulbright scholarship in order to study at Vanderbilt University receiving his Ph.D. in economics in 1971. While teaching at Chittagong University, Yunus observed the poverty epidemic in the rural villages around Chittagong and began a poverty reduction program which later became Grameen Bank. The bank, established in 1983, dealt specifically with the poor and marginalized loaning these citizens money in order to begin micro-enterprise. In 2006, Yunus and Grameen Bank received the Nobel Peace Prize.

How to Eliminate Poverty

This weekend I attended the Bottom Billions | Bottom Line Conference hosted by Seattle Pacific University’s Center for Integrity in Business. The event served as a convergence zone between business, nonprofit organizations, and the academy seeking to better understand ways that business can help alleviate world poverty.

Of the many interesting subjects discussed at the conference, the topic of microfinance seemed to continuously echo through my head. For those unfamiliar with the term, microfinance occurs when banks or nonprofit organizations loan small amounts to the poor, helping them to use these miniscule amounts of capital to begin income-generating endeavors.

Muhammad Yunus, founder of Grameen Bank and author of Banker to the Poor, observed that the only thing the poor lacked was opportunity.

He writes,

“When you hold the world in your palm and inspect it only from a bird’s eye view, you tend to become arrogant – you do not realize that things get blurred when seen from an enormous distance. I opted instead for “the worm’s eye view.” I hoped that if I studied poverty at close range, I would understand it more keenly.”

Charity vs. Microfinance

Without capital, the poor would take a loan from a moneylender at exorbitant rates in order to partake in the economy. At the end of the day, these people took home pennies to support a family. Yunus figured that if he could loan these slight sums at low interest rates, the poor could enjoy selling the products of their labor on the open market, thus creating economic capital and a trail out of poverty.

Charity, on the other hand, gives freely without expectation of return. Many, though, have suggested that pure charity does not eradicate poverty, because the poor become dependent on receiving aid. Blogger Filip Spagnoli aggregates international development aid on his website. The evidence he has compiled suggests that the amount of aid contributed to these developing nations is staggering, and yet economic growth is not a result.

Would development function differently if aid came in the form of a loan instead of charity? Yunus believes that loans to the poor provide the best investment.  Many stuck in the cycle of poverty are smart and hardworking; they just need the money to start. While big banks typically consider micro-loans to be both risky and inconsequential, Yunus’ experience argues that the poor possess the highest incentive to repay their loans.

Of course, when unforeseen problems such as natural disasters and economic meltdowns place the poor in positions where they are unable to repay the loan, Yunus extends grace and loans more money to help the poor back on their feet. In this way, microlending encourages entrepreneurial spirit. Where charity gives the widow a fish, microfinance engages in teaching the widow to fish.

What Is the Best Thing?

Although charitable giving in and of itself is never a bad thing, I do wonder if it is the best thing. Of course, a free gift without expectation of repayment carries the highest blessing for the receiver, yet long term, I wonder if microloans create a better society.  Certainly, charity is necessary for the destitute – the people who are so poor that any money loaned would be used to keep them from dying. Yet, the moderately poor need a kick start and microlending seems to be the best option in alleviating these struggles.

Yunus write Banker to the Poor in an autobiographical tone. He tries his best to position the book as a personal success story in the ongoing battle against poverty. It certainly seems like his position could and should be implemented worldwide, yet Yunus writes with a touch of humility. If you are interested in ways to eradicate poverty outside of giving to your favorite nonprofit, I suggest that you read this book.